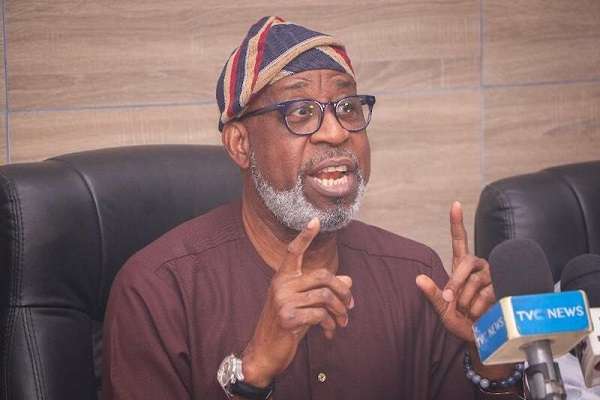
*Minister of Solid Minerals Development, Dr Dele Alake.
The landmark structural shake-up under the Nigeria Tax Act (NTA) of 2025 completely alters the country’s mining fiscal regime. Taking full regulatory effect on January 1, 2026, the new regime aggressively overhauls the decade-old fiscal framework previously governed by the Nigerian Minerals and Mining Act of 2007.
The President Bola Tinubu-led administration enacted these sweeping reforms to centralize federally collectable revenue and unlock the economic potential of the long-underperforming solid minerals sector. As a result, power has effectively split: the Nigeria Revenue Service (NRS) handles all financial collection and royalty administration, while the Ministry of Solid Minerals Development strictly retains technical and regulatory oversight.
The current fiscal framework shifts from absolute tax incentives toward structured, market-driven mechanisms:
Royalty Collection & Pricing Shifts:
In a major administrative change, the Nigeria Revenue Service (NRS) assumes the sole responsibility for collecting mineral royalties, migrating the process onto an end-to-end digital system. Crucially, royalties are now calculated based on an Official Selling Price tied directly to international trading platforms or marketplace metrics, rather than fixed historical values.
Transition from Tax Holidays to Tax Credits: The automatic three-to-five-year corporate income tax holiday under Section 28 of the previous Mining Act has been completely deleted. It is replaced by the Economic Development Tax Incentive (EDT Credit). The EDT Credit is an un-automatic, capital expenditure-linked credit that requires satisfying stringent qualification requirements.
Value Added Tax (VAT) Structural Overhaul: While mining exports remain zero-rated, the new act introduces a highly beneficial system allowing mining companies to claim input VAT on both operating and capital expenditures. This drastically eliminates the cascading taxes previously embedded in the supply chain.
Royalty Rate Hikes: To compensate for broader economic shifts, royalty rates—particularly for high-value priority minerals like gold—have been structured upward.
Tax professionals and legal consultants have mixed perspectives regarding the long-term effectiveness of the NTA.
On one hand, experts from international advisory firms like PwC Nigeria and global tax groups note that the harmonization of tax administration simplifies what was once a convoluted system. The elimination of cascading VAT and the explicit 30-day statutory timeline for the NRS to process valid refund claims are hailed as major alignments with international best practices.
Conversely, corporate legal consultants warn that deleting automatic tax holidays poses an immediate barrier to entry. Experts argue that because mining is heavily front-loaded with exploration costs, replacing predictable holidays with a complex, non automatic
EDT Credit mechanism could elongate Final Investment Decisions (FIDs) for prospective operators.
Macroeconomic Implications: Diversification and Leakage Controls
For the broader Nigerian economy, the tax law marks a triumphant pivot toward structural diversification.
Economic Dimension
Pre-Reform Era
Current Regime (Post-2026)
Revenue Collection
Fragmented across ministries, plagued by leakages.
Centralized under the NRS with strict digital monitoring.
Non-Oil Growth
Marginally contributed to the national treasury.
Surged significantly, driving multi-billion naira mining inflows.
Value Addition
Heavy raw material export with zero processing incentive.
Strong enforcement of local beneficiation and refining.
By forcing a tighter compliance environment, the federal government successfully checked historic capital flight. However, macroeconomic experts warn that if the infrastructure deficiency at mining sites is not solved simultaneously, higher taxes alone won’t sustain the sector’s projected contribution to the Gross Domestic Product (GDP).
For large-scale, corporate investors, the current regime represents a double-edged sword. The introduction of market-linked royalty pricing means that global market surges reflect immediately in corporate liabilities. While the clear-cut rules regarding the 100% repatriation of foreign currency profits remain an asset, the elimination of accelerated capital allowances forces corporations to rethink their financial projections. Institutional investors must now adapt to a high-scrutiny, strictly documented environment where regulatory box-checking is mandatory.
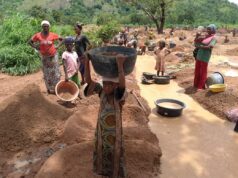
The segment feeling the sharpest friction under the current tax law is the artisanal mining sector, which historically comprises the vast majority of Nigeria’s local mining footprint.
The Formalization Trap: The current framework demands sophisticated accounting, monthly tracking of won/sold assets, and digital filing by the 21st of every month. Most artisanal miners operate informally and lack the corporate infrastructure to meet these rigorous reporting obligations.
Aggressive Compliance Pressures: With the NRS flexing its enforcement muscles to eliminate historic leakages, small-scale operations face heightened risks of severe penalties, closures, or aggressive formalization crackdowns.
Marginalization Risks: Because the newly minted EDT Credits favor massive capital expenditures, artisanal miners cannot effectively leverage the primary tax incentives available under the law. Experts fear this dynamic could inadvertently push struggling artisanal miners further into illegal, underground operations to evade the stringent tracking system.
The success of Nigeria’s mineral revolution hinges on striking a balance between revenue generation and local sector survival.